eResearch is pleased to publish an Update Report on DATA Communications Management Corp. (TSX: DCM | OTC: DCMDF).
We are maintaining our Buy rating and our one-year price target of $3.90.
You can download our 17-page Equity Research Update Report that covers an in-depth analysis of the company, an overview of recent financials, and our valuation methodology by clicking on the following link: eR-DCM-2026_11_16_UR-2026-Q3-FINAL
Company Overview:
DATA Communications Management Corp. (“DCM” or “the Company”) is a Canadian-based provider of marketing and business communication solutions to companies in North America. Its technology-enabled content and workflow management capabilities solve the complex branding, communications, logistics, and regulatory requirements of leading enterprises so its customers can accomplish more in less time. Its services include printing, content management, digital asset management (DAM), intelligent document processing (IDP), labels & asset tracking, location-specific marketing, social media analytics, and multimedia campaign management.
Report Highlights:
- Revenue Returns to Growth, In Line with Estimate: Revenue was $114.0 million in Q3/2026, up 8.2% from $105.4 million in Q3/2025, including organic revenue growth of 2.9% and the contribution of Octacom from July 8, 2026, and in line with our estimate of $114.6 million.
- Gross Margin Expands: Gross Profit was $30.2 million, up 22.7% year-over-year. Gross Margin of 26.5% increased 3.1 percentage points from 23.4% in Q3/2025 and came in above our estimate of 25.9%.
- SG&A Increases with Octacom: SG&A expenses were $21.9 million, up from $18.2 million in Q3/2025, primarily reflecting the inclusion of Octacom.
- Adjusted EBITDA Up 29%: Adj. EBITDA was $15.9 million (13.9% margin), up 29.0% from $12.3 million (11.7% margin) a year ago, driven by higher gross profit, a more favourable business mix, and the contribution from Octacom.
- Net Loss on Refinancing Costs: The Company reported a net loss of $2.9 million, compared to net income of $1.1 million in Q3/2025, reflecting a $3.0 million loss on extinguishment of debt and a $1.9 million net fair value loss on financial liabilities. Adjusted net income was $1.3 million, compared to $0.1 million in Q3/2025.
- Credit Facility Syndicated; Dividend Continues: In September 2026, DCM syndicated its $160 million credit facility with four Canadian Schedule I banks and added a $25 million uncommitted acquisition accordion. The Board declared its eighth consecutive quarterly dividend of $0.025 per share.
Investment Thesis:
The DCM Q3 2026 results reinforce the Company’s transition toward higher-margin, technology-enabled marketing and business communication solutions. Organic revenue growth of 2.9% marked a return to year-over-year growth, supported by new business activity, improving customer demand, and increased contributions from technology-enabled services. The improvement in gross margin to 26.5% and Adjusted EBITDA growth of 29.0% demonstrate the benefits of a more favourable business mix, disciplined pricing, and operational efficiencies.
The acquisition of Octacom on July 8, 2026, expands DCM’s capabilities in intelligent document processing, workflow automation, and digital transformation. Octacom contributed $5.6 million in revenue during the quarter and generated more than $1.5 million in net new business opportunities across several sectors. The opening of a U.S. intelligent document processing centre in the Chicago area and early cross-selling wins through existing DCM customer relationships support the Company’s strategy of expanding its technology-enabled services and recurring revenue opportunities.
DCM’s financial position reflects increased borrowing following the Octacom acquisition and the refinancing of its former Fiera Private Debt facilities. At September 30, 2026, net debt excluding lease liabilities was $110.7 million, while the Company remained compliant with its financial covenants. Operating cash flow for the first nine months increased to $27.3 million from $16.8 million a year earlier. Management expects organic revenue growth to continue in Q4/2026, supported by new business wins, improving customer demand, and the continued contribution from Octacom. Key risks include the successful integration of Octacom, debt reduction, trade policy uncertainty, tariffs, and broader economic conditions.
Financial Analysis & Valuation
- We estimate an equal-weighted price target of $3.89 based on a DCF valuation ($4.05/share), a Revenue Multiple valuation ($3.74/share), and an EBITDA Multiple valuation ($3.89/share).
- We are maintaining our Buy rating and our one-year price target of $3.90.
You can download our 17-page Equity Research Update Report by clicking on the following link: eR-DCM-2026_11_16_UR-2026-Q3-FINAL
FIGURE 1: Historical Results and Future Estimates
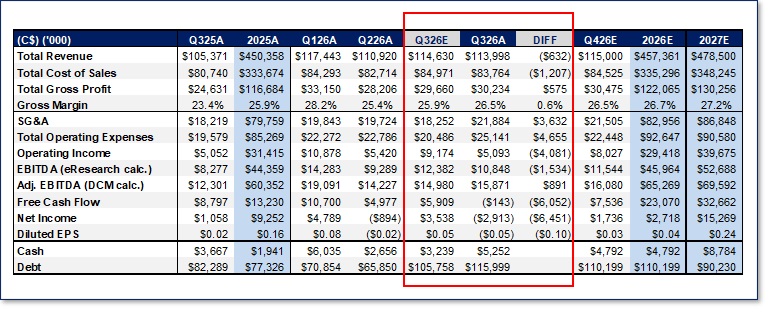
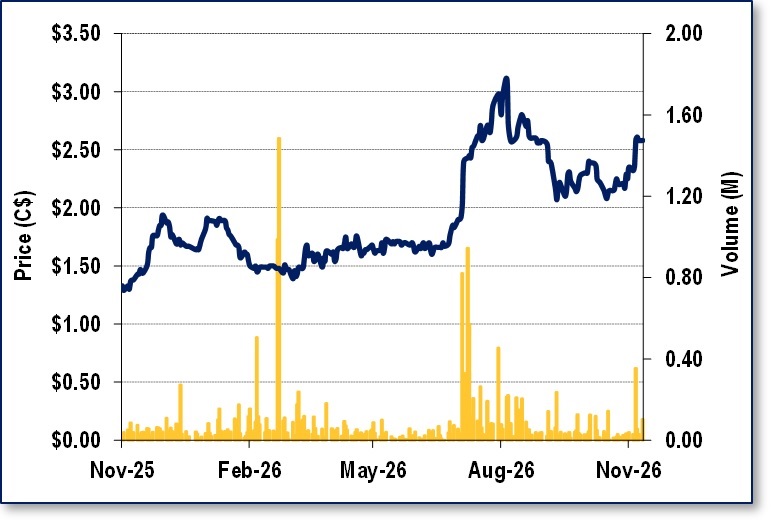
FIGURE 2: 1-Year Stock Chart
Notes: The author, employees, consultants, and family of eResearch may own stock positions in companies mentioned in this article, report, and/or video, and may have been paid by a company mentioned. eResearch offers no representations or warranties that any of the information contained in this article is accurate or complete. Content on eresearch.com is provided for general informational purposes only and does not constitute financial, investment, tax, legal, or accounting advice, nor does it constitute an offer or solicitation to buy or sell any securities referred to. Individual circumstances and current events are critical to sound investment planning; anyone wishing to act on this information should consult with a financial advisor. The article may contain “forward-looking statements” within the meaning of applicable securities legislation. Forward-looking statements are based on the opinions and assumptions of the Company’s management as of the date made. They are inherently susceptible to uncertainty and other factors that could cause actual events/results to differ materially from these forward-looking statements. Additional risks and uncertainties, including those that the Company does not know about now or that it currently deems immaterial, may also adversely affect the Company’s business or any investment therein. Any projections given are principally intended for use as objectives and are not intended, and should not be taken, as assurances that the projected results will be obtained by the Company. The assumptions used may not prove to be accurate, and a potential decline in the Company’s financial condition or results of operations may negatively impact the value of its securities. Please read eResearch’s full disclaimer.