eResearch is pleased to publish an Update Report on DATA Communications Management Corp. (TSX: DCM | OTC: DCMDF).
We are maintaining a Buy rating and a one-year price target of $3.90.
You can download our 16-page Equity Research Update Report that covers an in-depth analysis of the company, an overview of recent financials, and our valuation methodology by clicking on the following link: eR-DCM-2026_08_19_UR-2026-Q2_FINAL
Company Overview:
DATA Communications Management Corp. (“DCM” or “the Company”) is a Canadian-based provider of marketing and business communication solutions to companies in North America. Its technology-enabled content and workflow management capabilities solve the complex branding, communications, logistics, and regulatory requirements of leading enterprises so its customers can accomplish more in less time. Its services include printing, content management, digital asset management (DAM), intelligent document processing (IDP), labels & asset tracking, location-specific marketing, social media analytics, and multimedia campaign management.
Report Highlights:
- Revenue Decline Moderates, Below Estimate: Revenue was $110.9 million in Q2/2026, down 2.5% from $113.8 million in Q2/2025, a slower rate of decline than 5.0% in Q1/2026, but below our estimate of $112.5 million.
- Gross Margin Compression Continues: Gross Profit was $28.2 million, down 7.5% year-over-year. Gross Margin of 25.4% decreased 1.4 percentage points from 26.8% in Q2/2025 and came in below our estimate of 26.0%.
- SG&A Discipline Holds Steady: SG&A expenses were $19.7 million, down 0.7% from $19.9 million in Q2/2025 and essentially unchanged from $19.8 million in Q1/2026, at 17.8% of revenue.
- Adjusted EBITDA Retreats from Record Q1 High: Adj. EBITDA was $14.2 million (12.8% margin), down 14.1% from $16.6 million a year ago, primarily due to lower revenue and gross profit, but partially offset by lower SG&A expenses resulting from cost-control and operating-efficiency initiatives.
- Net Loss in Quarter: The Company reported a net loss of $0.9 million, compared to net income of $3.7 million in Q2/2025, reflecting acquisition & restructuring costs and a $1.1 million net fair value loss on financial liabilities.
- Octacom Acquisition Closes; Debt Reduction and Dividend Continue: DCM completed its $54.0 million acquisition of Octacom on July 8, 2026, funded through an amended $160 million credit facility. Company-defined Net Debt was $64.6 million, down 26.2% year-over-year, and the Board declared its seventh consecutive quarterly dividend of $0.025 per share.
Financial Analysis & Valuation
- We estimate an equal-weighted price target of $3.90 based on a DCF valuation ($4.13/share), a Revenue Multiple valuation ($3.78/share), and an EBITDA Multiple valuation ($3.70/share).
- We are maintaining our Buy rating and our one-year price target of $3.90.
- We are maintaining a Buy rating and a one-year price target of $3.90.
You can download our 16-page Equity Research Update Report by clicking on the following link: eR-DCM-2026_08_19_UR-2026-Q2_FINAL
FIGURE 1: Historical Results and Future Estimates
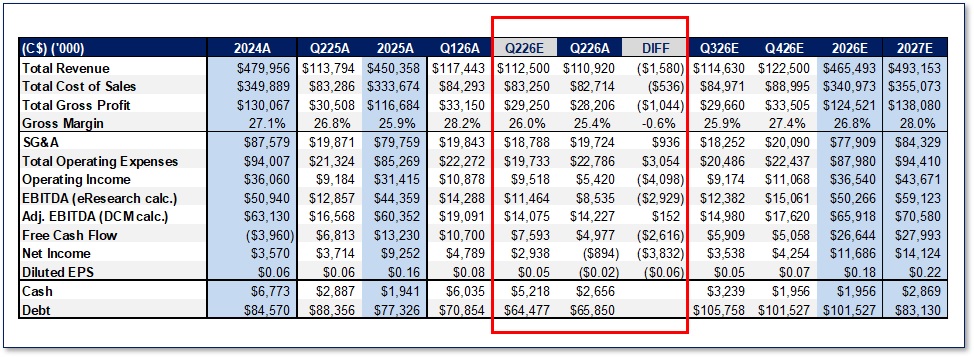
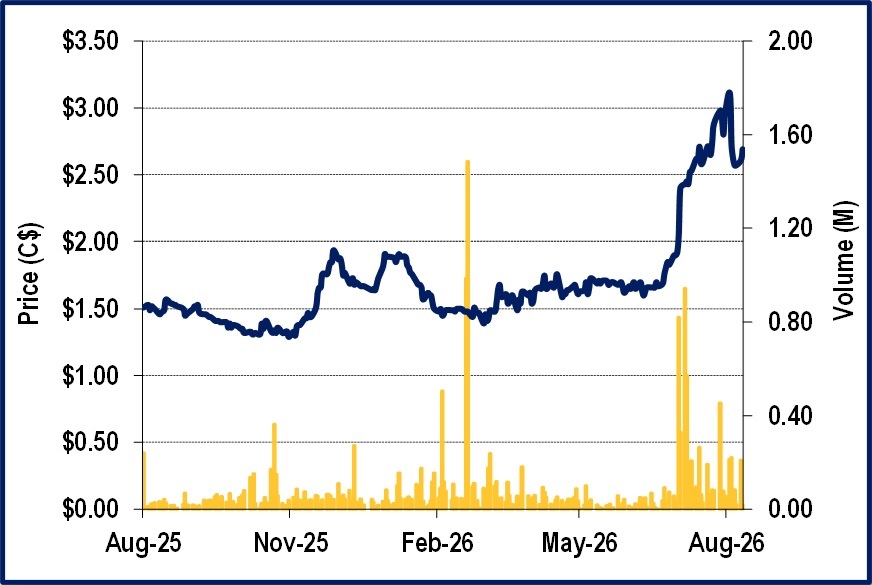
FIGURE 2: 1-Year Stock Chart
Notes: The author, employees, consultants, and family of eResearch may own stock positions in companies mentioned in this article, report, and/or video, and may have been paid by a company mentioned. eResearch offers no representations or warranties that any of the information contained in this article is accurate or complete. Content on eresearch.com is provided for general informational purposes only and does not constitute financial, investment, tax, legal, or accounting advice, nor does it constitute an offer or solicitation to buy or sell any securities referred to. Individual circumstances and current events are critical to sound investment planning; anyone wishing to act on this information should consult with a financial advisor. The article may contain “forward-looking statements” within the meaning of applicable securities legislation. Forward-looking statements are based on the opinions and assumptions of the Company’s management as of the date made. They are inherently susceptible to uncertainty and other factors that could cause actual events/results to differ materially from these forward-looking statements. Additional risks and uncertainties, including those that the Company does not know about now or that it currently deems immaterial, may also adversely affect the Company’s business or any investment therein. Any projections given are principally intended for use as objectives and are not intended, and should not be taken, as assurances that the projected results will be obtained by the Company. The assumptions used may not prove to be accurate, and a potential decline in the Company’s financial condition or results of operations may negatively impact the value of its securities. Please read eResearch’s full disclaimer.